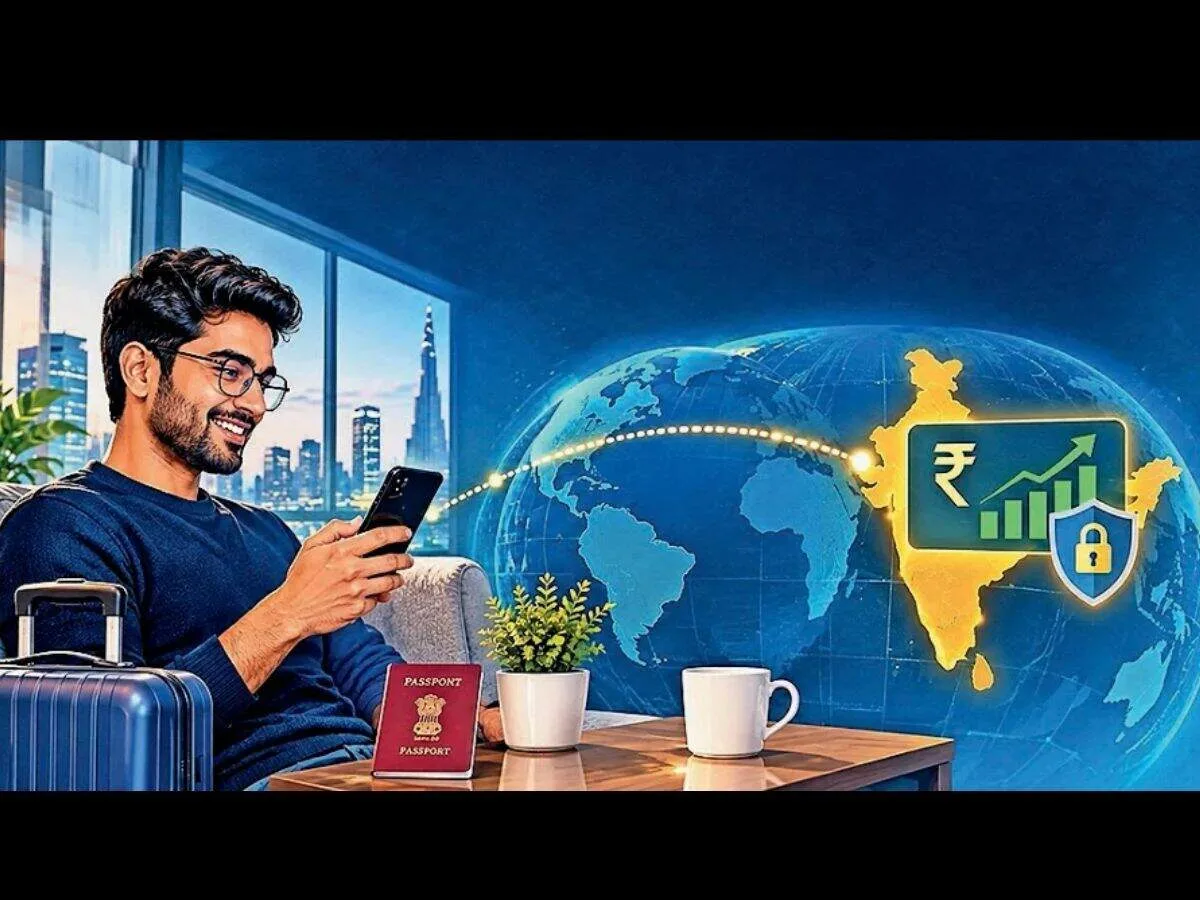
In a significant move aimed at facilitating investments by Indian expats, the Securities and Exchange Board of India (SEBI) has recently issued a circular permitting Non-Resident Indians (NRIs) and Overseas Citizens of India (OCIs) to conduct their Know Your Customer (KYC) procedures online from countries recognized by the Financial Action Task Force (FATF). This development is expected to streamline the investment process for Indians living abroad, allowing them to open investment accounts without the need to travel back to India.
This new circular is a game changer for NRIs, who previously faced considerable hurdles when attempting to partake in Indian markets. The ability to meet KYC requirements online means that potential investors can navigate an otherwise complex process from the comfort of their current locales. By broadening the reach of digital KYC registration, SEBI recognizes the evolving nature of global financial transactions, particularly in a post-pandemic world where digital solutions have gained prominence.
For the UAE and Gulf region, where a significant number of Indian expatriates reside, this initiative is particularly impactful. The UAE is home to one of the largest Indian expatriate populations globally, contributing substantially to the economy through remittances and investments. Simplifying the KYC process is likely to encourage more investments into India’s robust market, fostering a stronger economic relationship between India and the Gulf states.
Compared to other markets, India has been relatively slower in adopting fully digital KYC processes, relying heavily on physical documentation and in-person verification. However, with this recent circular, India is aligning itself closer to international standards. Countries like Singapore and the UK have already set the precedent for online KYC, making it easier for investors from around the world to engage with their financial systems. By adopting similar strategies, India could enhance its attractiveness as an investment destination amid growing competition.
Furthermore, this shift towards digitalization is likely to have ripple effects across the financial services industry in India. As financial institutions adapt to these changes, it may lead to further innovations in how services are offered to NRIs and OCIs. This transformation could potentially drive down operational costs for these firms while also improving client experiences, ultimately benefiting all parties involved.
Looking ahead, the significance of digital KYC procedures for NRIs cannot be overstated. As financial systems worldwide continue to embrace technology, the move towards ease of access and streamlined processes will likely become a standard expectation rather than an exception. This development could pave the way for greater regulatory adaptations and perhaps even a revision of more traditional practices in the Indian financial sector, emphasizing the need for India to remain competitive in attracting foreign capital.
Leave a Reply